7 July 2026
Diaceutics LON:DXRX
Reccomendation: Buy, hold. Today's price 145p /Target price 170p for 17.2% minimum. 70% likelihood of much bigger upside due to acquisition rumours (within next 6 months pobably) .
Who are they: Headquartered in Belfast, Northern Ireland, Diaceutics PLC is a leading technology and data analytics provider specializing in the commercialization of precision medicine diagnostics.
Ai Analysis: -ignore all, this is absolute non-commital rubbish typical drivel written by LLMs, but it's funny how it does a horoscope-like stock analysis- :
"I’ll assess Diaceutics as an equity, not merely as an attractive technology: current valuation, revenue quality, cash position, growth durability, dilution risk, and what must go right for the shares to outperform."
full... Diaceutics looks like an attractive business, but the shares are not yet a low-risk investment. At roughly 146p per share, corresponding to a market capitalisation of about £124 million, I would classify it as a promising speculative small-cap position, rather than a company in which to immediately build a large holding.
At around 146p, my view would be:
Suitable for: a small, long-term speculative position built gradually.
Not yet suitable for: a large or high-conviction position based solely on the platform story.
If you ask Google Gemini Pro how the company makes money: (good luck understanding this waffle)
Diaceutics' Unique Selling Proposition (USP) centers on its proprietary DXRX – The Diagnostic Network®, which stands as the world's first diagnostic commercialization platform. This platform integrates massive pipelines of real-world, real-time testing data from a global network of thousands of laboratories to bridge the fragmented gap between drug launches and patient testing, ensuring that individuals receive the right treatment at the right time.
Alex's Analysis:
What this company actually does? this company steals patient data and sells it to big pharma. And it's a good business model, with few costs, good margins and reliable clients. The signals are acually hidden in the "Other risks" section of the LLM analysis:
-"Risky customer concentration, 93% of revenue in North America/American clients": this is actually good, it's where all the money is made
-"one single customer generated 18% of total revenue" : this is good also, it means they're dealing with BIG clients, big pharma is willing to pay them a lot for what they do.
-"Gross margin fell": yes form 88% to 82%, this is actually really good margins.
They had a recent high of 170p , that's where target price came from. They will get back there easy. In addition I've been hearing good things about this company within the industry, with some credible opinions that Diaceutics will actually become an acquisition target very soon, and I tend to believe it because if pharma pays them that much for info, it means they are generating higher revenue from that information. It would be like a single Hedge Fund paying me 1.3M for research data, the hedge fund would likely acquire this research team. #
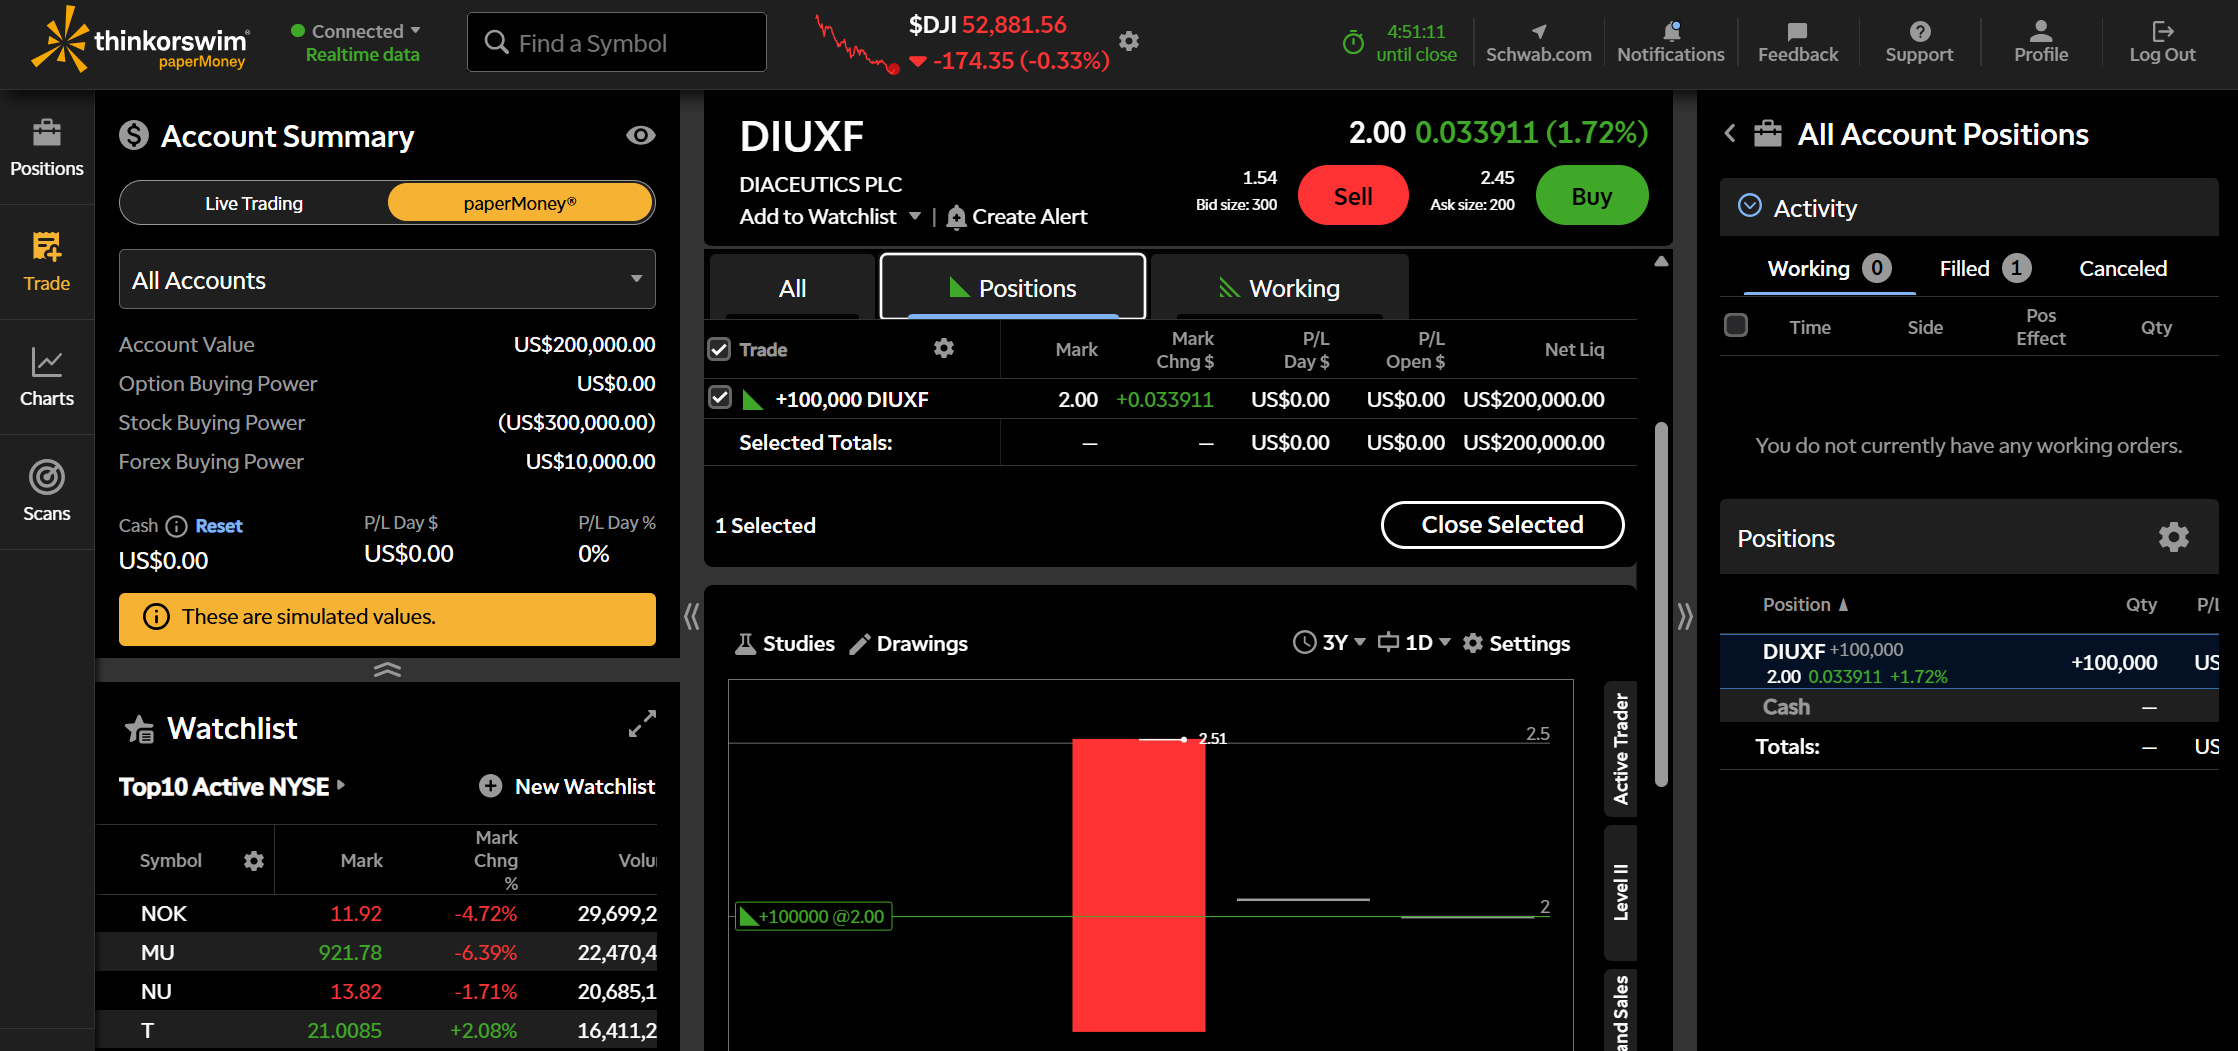
Position: In addition to make it more interesting and material I've created a paperMoney (virtual trading account) to help me track how the positions and advise plays out. 100K of DIUXF (the OTC Nasdaq ticker for the LSE listed DXRX equivalent):
10/8/2026 -Monthly update -
Since the original post 7th Jul, Canaccord Genuity gave it a "Buy" with a target of 215, on the 30th Jul. So, someone out there agrees with me...is Canaccord legit? https://www.theglobeandmail.com/investing/markets/markets-news/Tipranks/3553792/diaceutics-diuxf-receives-a-buy-from-canaccord-genuity/
They are probably reacting to previous day (29th) report of "75% Surge in ARR and 22% Revenue Growth in H1 2026" https://kalkinemedia.com/uk/news/announcements/diaceutics-reports-75-surge-in-arr-and-22-revenue-growth-in-h1-2026-amid-precision-for-all-market-expansion
These new data and recs improve the chances of hitting our predicted target.
14/09/2026 -Monthly update-
The stock is up since the entry point. Today's return at market close +9.54% (up since initial post), at a share price of 160p. They have announced that they will do a "live" half year financial results webinar with analysts later this month on 22nd Sept. Announcements are linked to volatility, so if searching returns around the 10% mark, you could get off the ride now. If happy with the volatility continue to hold. I predict results will be good, and a good chance it hits the 170p target afterwards.